What is a reinstatement cost assessment?
A reinstatement cost assessment is a calculation of what it would cost to rebuild a property from scratch if it were destroyed. It sets the declared value on a buildings-insurance policy, and covers construction cost plus demolition, professional fees, statutory charges and inflation. It is not the market value — land is excluded.
- Basis
- The RICS professional standard on reinstatement cost assessment of buildings. Costs are commonly built up from RICS BCIS rebuilding cost data, using the BCIS Standard Form of Cost Analysis element categories.
- Produced by
- A chartered surveyor with relevant building-cost experience — typically a building surveyor or quantity surveyor (MRICS or FRICS), who signs the assessment.
- Who it goes to
- The property owner and their insurer or broker. It supports the declared value, and through it the sum insured, at renewal.
- What it excludes
- Market value. The condition of the building. Contents, plant and machinery, tenant's fit-out. Loss of rent and business interruption. And the land — you still own the plot after a fire.
What a reinstatement cost assessment looks like
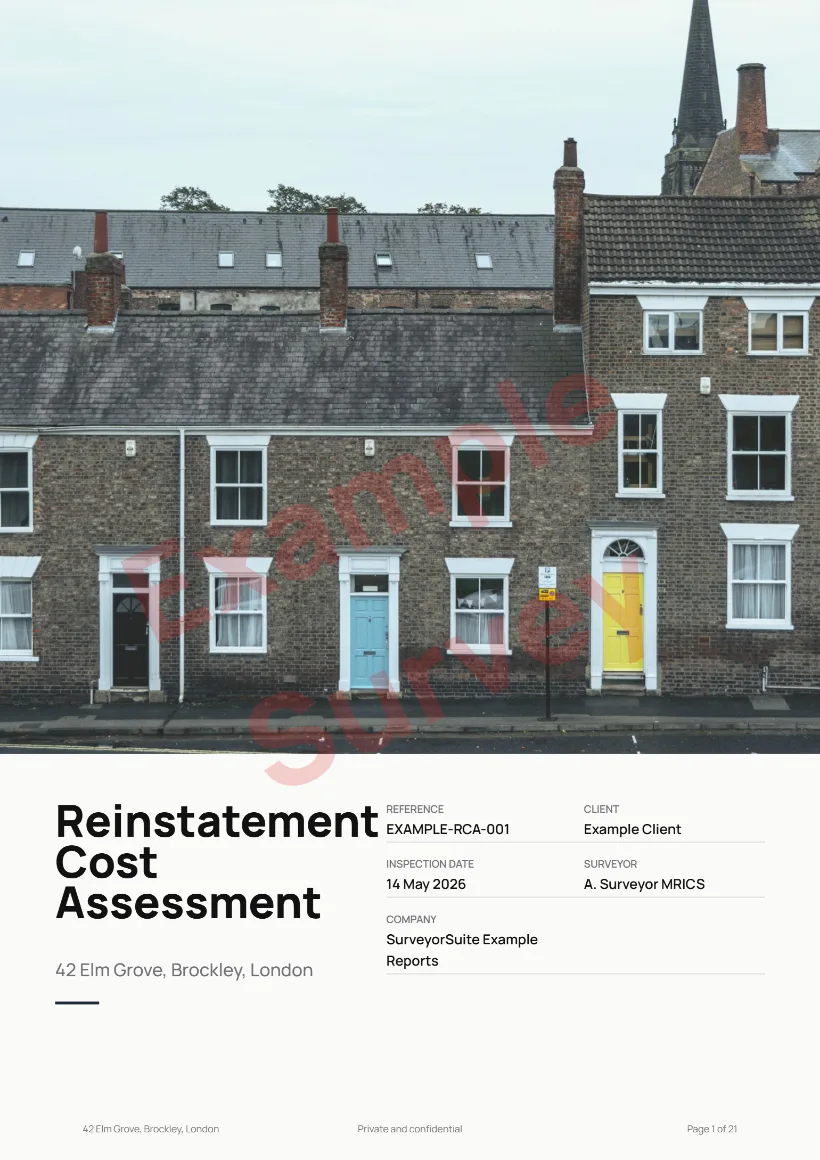
Scroll through a complete assessment, from the elemental build-up to the headline figure. The notes alongside explain each part as you go. The content is fictional and the photos are placeholder slots.
Loading example…
Styled to your firm
Your logo and accreditation marks, your brand colours, and your choice of cover, header, footer and photo layout. Set it once in Settings and every report follows.
Or your own report, built for you
Keep the format your firm already uses: we recreate it as a private template, or build a report type we don’t list. You approve a real PDF before you sign up. Bespoke report templates →
What goes in a reinstatement cost assessment
Eight sections, A to H. The middle three do the work: an element-by-element build-up, the adjustments that sit on top of it, and the totals that fall out.
- AInstruction detailsSurveyor and qualifications, client, insurer and policy number, inspection date and the base date the costs are calculated at, the purpose, the basis of assessment (Day One, inflation-inclusive, indemnity and others), and exactly what extent of property is being assessed.
- BProperty descriptionAddress, UPRN, property type, age, tenure and the general description of what is being insured.
- CBuilding detailsGross internal area and the measurement standard used, storeys, ceiling heights, basements and foundations, wall / roof / floor construction, finishes, each service in turn, outbuildings, boundary structures and any special features.
- DElemental cost breakdownOne line per element on the BCIS Standard Form of Cost Analysis categories — substructure, frame, roof, external walls, finishes, each services group, external works, drainage, preliminaries, overheads and contingencies — each with a quantity, a rate and a line total.
- EAdjustments & additional costsDemolition and site clearance, shoring, professional fees with a tier and an optional consultant-by-consultant breakdown, planning and building control fees, an inflation provision with the index and base date used, the VAT recoverability position, and the BCIS regional location factor applied.
- FCost summaryBuilding cost total and the derived rate per square metre, external works, subtotal, the design and consent period and the construction period, the total reinstatement figure in numbers and in words, the effective date, inclusions and exclusions, and the recommended review cadence.
- GAssumptions, limitations & caveatsThe mandatory caveats, each confirmed by the surveyor: this does not comment on the condition of the property; it has no direct relationship to market value; it is prepared for insurance purposes only; it relates to building insurance alone. Plus specific exclusions, contamination commentary and the cost data source cited.
- HDeclarationSigned declaration, qualifications, methodology summary, and the disclosure of any AI assistance used in drafting.
When a reinstatement cost assessment is commissioned
The trigger is usually an insurance renewal. If the sum insured is set too low, most policies apply the average clause: the insurer scales any claim, even a small partial one, down by the same proportion the building was underinsured. Insure a building for half its true rebuild cost and a £100,000 fire claim can be settled at £50,000. A properly evidenced assessment is the defence against that. For the full background, see our guide: What is a reinstatement cost assessment?
Renewal, and the broker asks
The figure on the schedule has been carried forward and indexed for years, and nobody has checked it against a real build-up. A commercial policy, a block of flats or a managing agent's portfolio is where the question gets asked hardest, because the exposure is largest.
Listed and non-standard buildings
Published rates are built for conventional construction. Heritage fabric, hand-made materials and traditional trades can cost several times the standard rate to reinstate, and professional fees run higher too — so these need a bespoke build-up rather than a straight per-square-metre figure.
The last one is years old
Rebuild costs move with construction inflation, so a one-off assessment ages. Common practice is a full professional reassessment periodically — often every three years — with the figure indexed annually in between. A building that has been extended, altered or changed use should be reassessed sooner.
Reinstatement cost is not market value
This is the point clients most often get wrong, and it is one of the caveats the surveyor has to confirm on the face of the assessment. Three different questions, three different documents.
| Comparison | Reinstatement cost assessment | Market valuation | Condition survey |
|---|---|---|---|
| Question it answers | What would it cost to rebuild this? | What would this sell for? | What is wrong with it? |
| Is the land included? | No — you still own the plot after a fire | Yes — location is most of the figure | Not a monetary figure at all |
| Who it is for | The insurer or broker, to set the declared value | A buyer, seller, lender or investor | A buyer, owner or occupier |
| How it is derived | Elemental build-up from rebuild cost data, plus allowances | Comparable evidence and market analysis | Inspection and professional judgement |
| Does it comment on condition? | No — explicitly caveated out | Only so far as it affects value | Yes, that is the whole point |
| How the figures relate | Unrelated to market value — can be far above or far below it | Unrelated to rebuild cost | — |
A modest terrace in an expensive city can be worth far more than it costs to rebuild; a large, remote or architecturally complex building can cost far more to rebuild than it would ever sell for. For valuation work see Level 2 with Valuation; for condition see Level 3 Building Surveys.
How SurveyorSuite produces a reinstatement cost assessment
SurveyorSuite is report-writing software for UK surveyors. The elemental structure, the allowances and the mandatory caveats are built in, and the totals are calculated for you rather than maintained in a spreadsheet alongside the report.
AI drafts the description. The figure is arithmetic, not AI.
Dictate or type your measurements and specification notes. The AI turns them into the building description, the methodology narrative and the rationale behind the allowances you have chosen.
What it does not do: produce the rebuild figure. You set the rates, the regional factor and the allowance percentages; the built-in calculator totals every element and on-cost into the headline figure and the rate per square metre. The AI works only from what you wrote — it does not invent materials, measurements or specification. AI use is disclosed in Section H and timestamped in the audit trail. The feature is optional; the software works the same way without it.
Read our full AI compliance position- Sections A–H built in
- BCIS Standard Form of Cost Analysis element categories
- Quantity × rate × line total, added up for you
- Allowances, regional factor and VAT position as structured fields
- Mandatory caveats confirmed before export
- Bulk import from the camera roll
- Drag each photo to its section
- Arrow, box and label annotations
- Numbered appendix with two-way Fig. links
- Works offline on iOS and Android, syncs later
- Branded PDF with your logo and colours
- Word (.docx) export for further editing
- Cost data source recorded so a reviewer can replicate it
- Client database and audit trail
- Cloud archive for long-term retention
SurveyorSuite is £35 a month on your own, or £35 per paid seat with colleagues (£30 per paid seat on annual billing, ex-VAT), with all 16 report types and unlimited reports included.
Reinstatement cost assessment FAQs
Is the reinstatement cost the same as the market value?
What is the declared value, and how does Day One differ from index-linking?
What data drives the cost rates?
Are demolition and professional fees included?
How often should a reinstatement cost assessment be refreshed?
Is there a free reinstatement cost calculator or template?
Who can prepare a reinstatement cost assessment?
Does the AI calculate the rebuild figure?
What happens to my notes? Are they used to train AI models?
Write reinstatement cost assessments in SurveyorSuite
£35 a month solo, £35 per paid seat for a team. All 16 report types, unlimited reports.
1-month free trial · card captured, nothing charged during the trial · cancel any time
Last reviewed: · General information for professionals, not insurance or legal advice. Policy wordings, the operation of any average clause and current RICS guidance all vary — always work to the actual policy and the guidance current at the time. SurveyorSuite is not an insurer or broker and is not affiliated with or endorsed by RICS or BCIS.